

Estate planning can help protect your wishes, loved ones and assets at any age. Here’s how Gen X, millennials and Gen Z can approach planning now and update it as life changes.
Learning Center / Financial Planning / Why Estate Planning for Gen X, Millennials and Gen Z Is Crucial
Why Estate Planning for Gen X, Millennials and Gen Z Is Crucial
Key takeaways
- Estate planning can help people at all life stages document their wishes.
- Gen X may focus on executors, healthcare proxies, powers of attorney, beneficiaries and legacy goals.
- Millennials with families may need to plan for guardianship and long-term financial support for children.
- Gen Z adults may start with a simple plan that includes early assets, digital accounts, and future changes.
- Estate plans should be reviewed after major life events and updated regularly.

Estate planning isn't just something to worry about later in life.
No matter your age, or where you are on your financial journey, it's critical to ensure your legacy follows your wishes and best takes care of those you leave behind.
For Gen X, Millennials, and Gen Z, it's never too early to start, and these scenarios illustrate how comprehensive estate planning can be tailored and changed as your circumstances evolve.
Gen X (45 to 60 years old)
Gen X is the standard demographic that you see coming for estate planning.
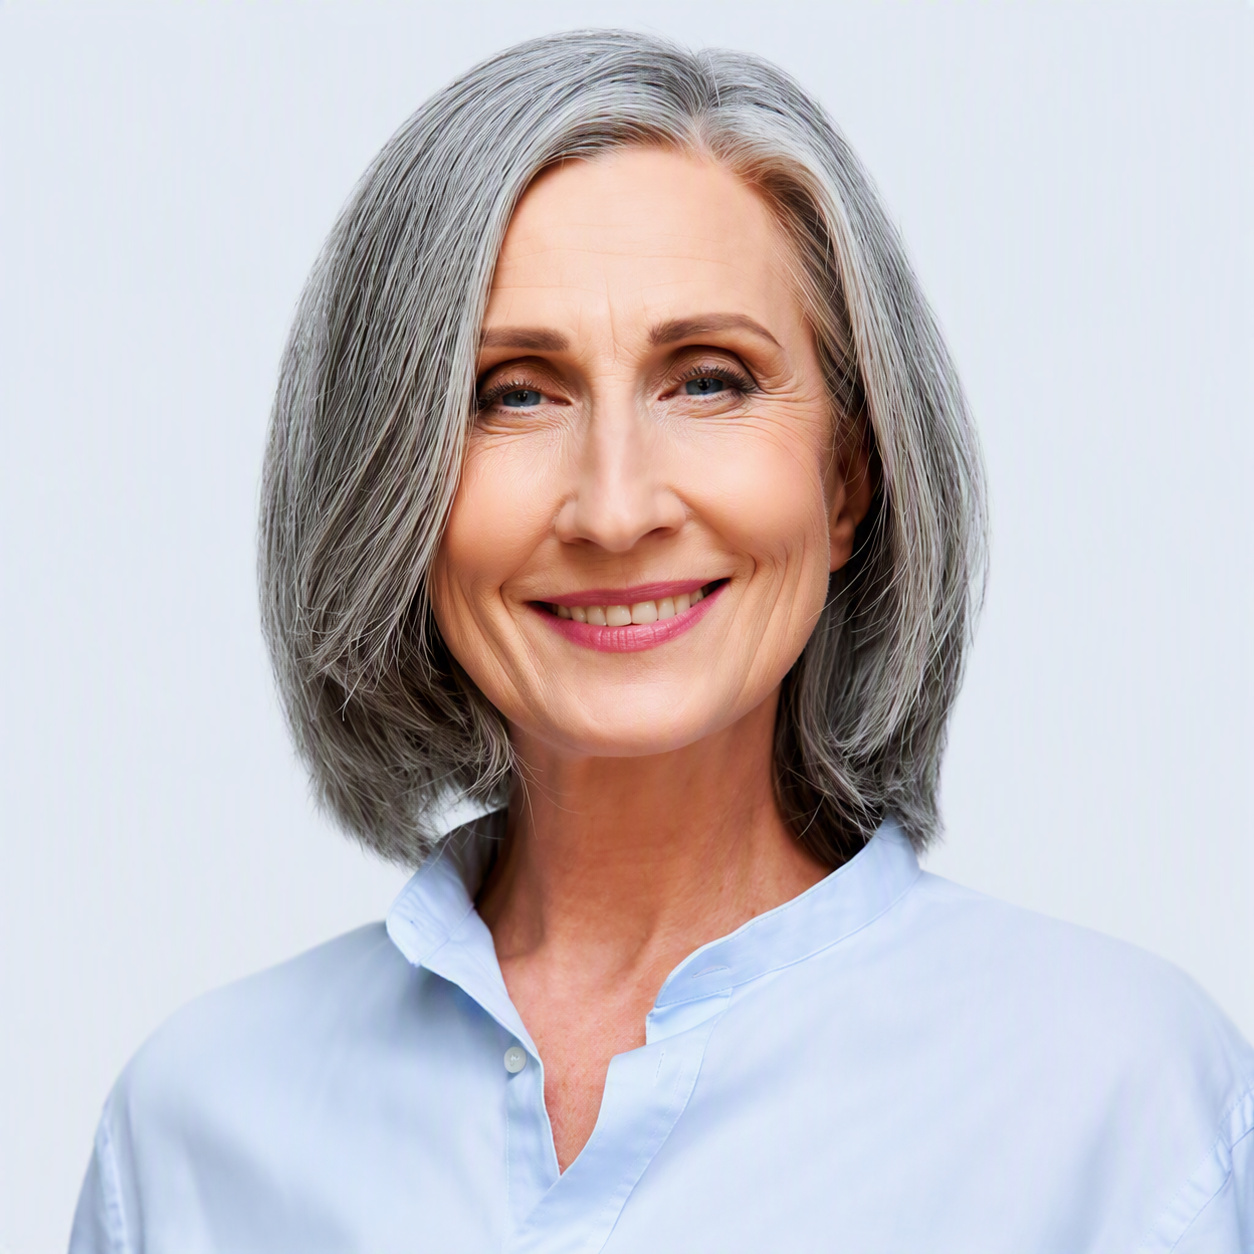
Estate planning considerations for Gen X —Meet Britney
She has two kids in college, married for over 30 years and is about a decade away from retirement. She's a little anxious as she hasn't done any estate planning yet but knows it needs to be a major priority.
"Gen X is the standard demographic that you see coming for estate planning," said Dan Loftus, Wealth Strategist at TD Wealth.
Dan adds that the importance of the estate planning process is helping our loved ones plan for what's going to happen after we're gone.
"When you're in your 50s or 60s, you probably have some people who are dependent upon you in some way and when someone passes away or becomes incapacitated, it's a very emotional time for the family," Dan added. "Setting up the documents and writing out the instructions for them can help provide a roadmap and make things easier."
Dan, who is a former estate planning attorney, said it's important to think of a few things, including who will be the executor of the will — the person who's going to read the documents, go to court, sign everything that's necessary and execute the will.
"But for Gen X, a successor executor is just as important," Dan said. "A lot of times we see spouses nominate each other but then never return back to the estate planner to update their documents after the first spouse dies. Then our documents haven't been updated to reflect who's going take over now."
Dan tells his clients to think about estate planning like a doctor's appointment: come in every couple of years and make sure everything is up to date.
"Another thing to consider is who will be your healthcare proxy," Dan said. "The healthcare proxy and the durable power of attorney are who's going to step in for us if something happens to make us incapacitated. "And those are different decisions than the executor. So, it's good to have a different person in mind for these decisions."
Finally, when it comes to the will itself, there are two items to consider — are you trying to take care of beneficiaries or are you considering leaving a legacy and thinking about charities?
"At this point in life, we're thinking about who we want to help and how we can help them," Dan said. "Every state in the United States has a different level of estate taxes if they have them. So, through estate planning, you can work to make sure that the largest amount of your assets are going to pass to your beneficiaries."
Millennials (29 to 44 years old)
Millennials typically are thinking less about legacy and more about young children or spouses.
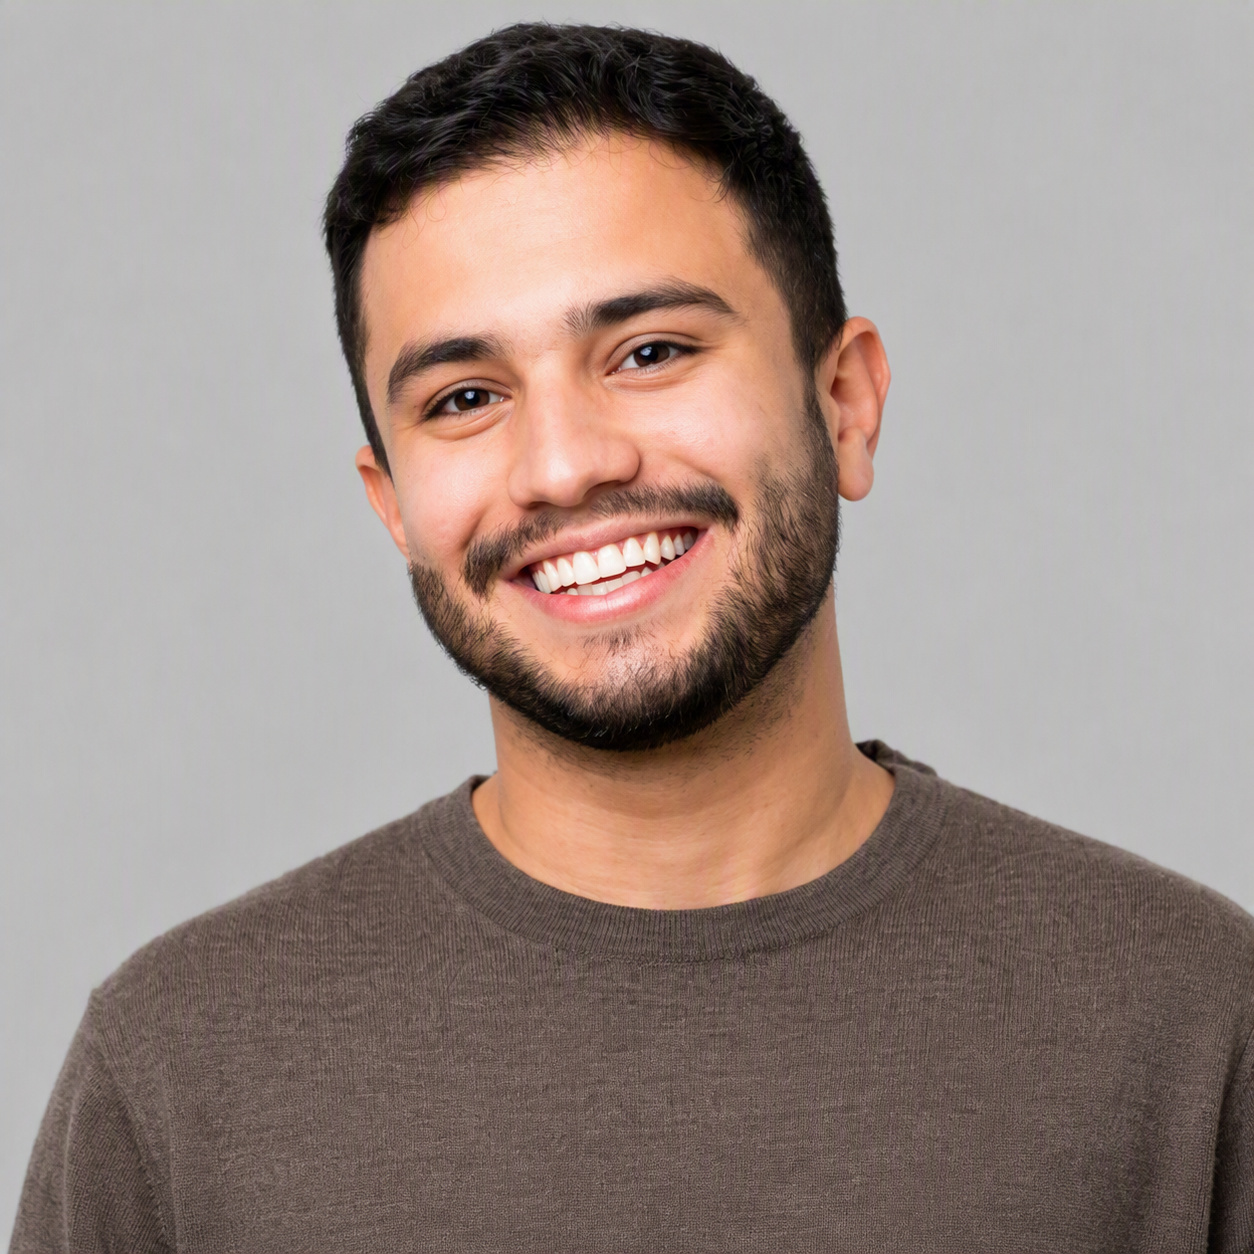
Estate planning considerations for millennials — Meet Dan
An accomplished lawyer and bank advisor, who has a 2-year-old son and is starting to think about making sure he’s taken care of, even though he's not thinking about retirement just yet.
"I'm millennial. I'm a great example," Dan said. "I have a 2-year-old and of course, we made sure to put a plan in place right after he was born."
Dan says for this age group, you’re probably thinking less about legacy and more about young children or spouses.
"We're still talking about all the same documents, a will or potentially a trust depending on your state, durable power of attorney and a healthcare proxy. But for both parents, we're also thinking about guardianship in case something happens to both parents," he added.
In addition to planning on who will take care of the child, the other questions to consider include do you want the estate to keep your home so that the child will grow up in the family home, etc.
You also might want someone different to be the financial guardian, like a lawyer or financial advisor, for the child as opposed to the personal guardian, the person who will physically raise the child.
"Someone who manages the assets, who helps them be invested, helps them over the course of time," he said.
"You and this financial guardian will also decide on how to pass those assets to your child so that they last in a manner that can be as effective as possible for as long as possible without you."
For millennials, they aren't locked into any plan, as they can also adjust and change their will every few years as needed. Considerations will be different over time.
"You might have another child, your assets might grow, you might move," Dan said. "But waiting to do your estate planning is the danger. If you never do anything and something happens, the state might decide the plan for you."
Elder Gen Z (25 to 30 years old)
Gen Z will grow into their estate plan as they get older.
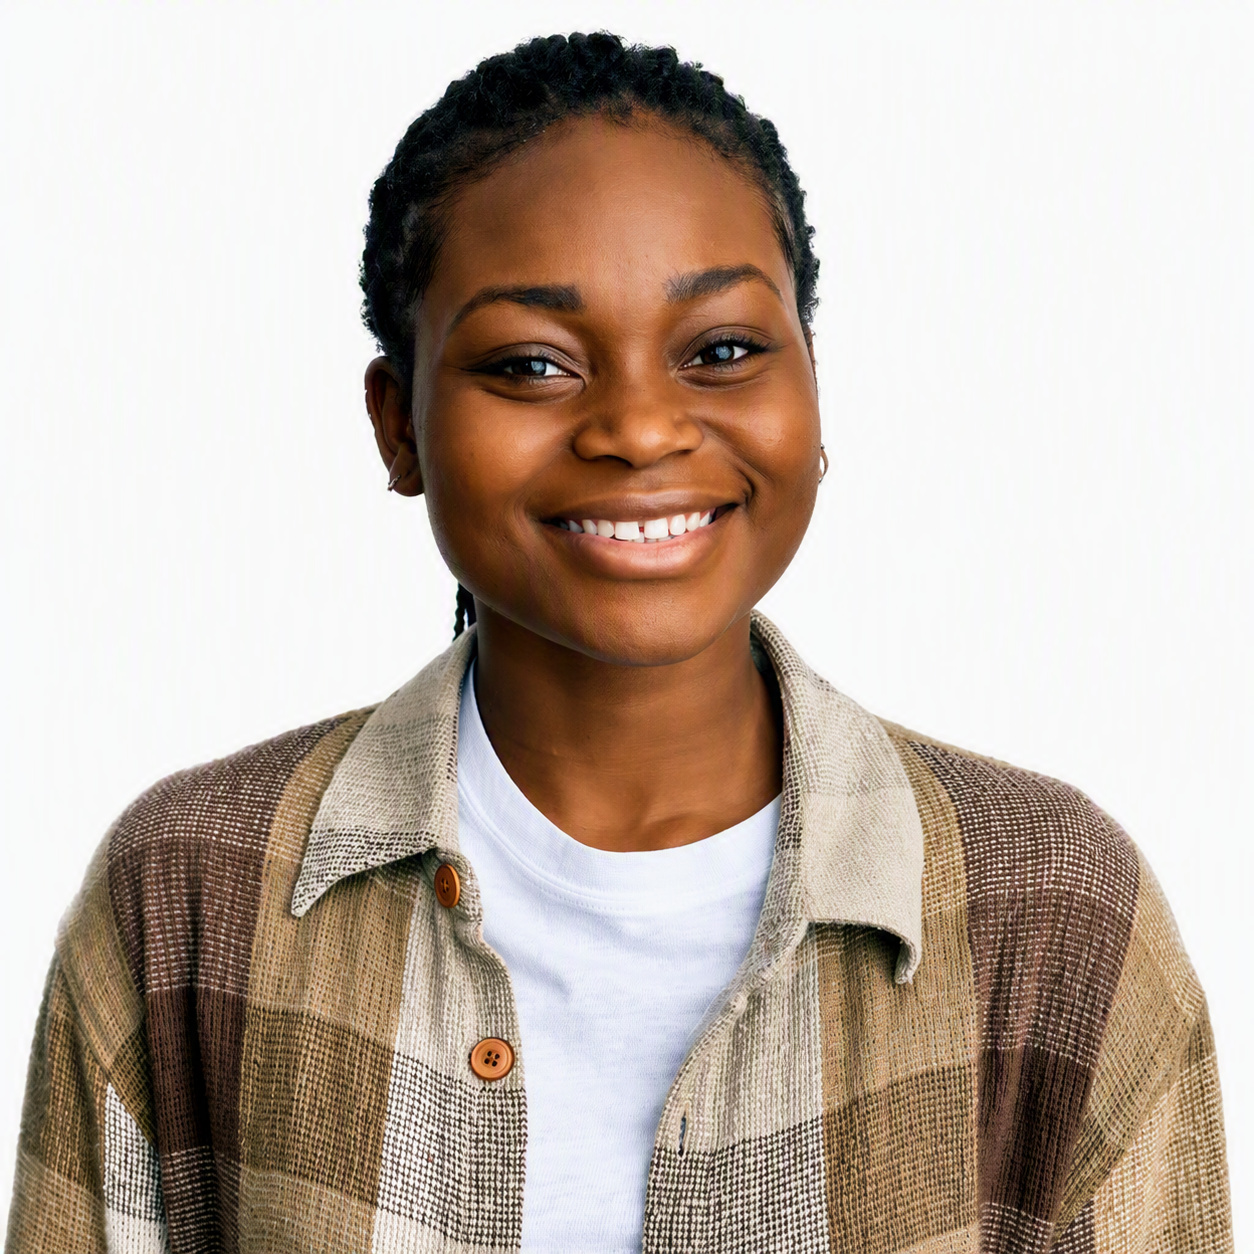
Estate planning considerations for Gen Z — Meet Megan
She’s fresh out of graduate school, just starting her career off, has invested in crypto, has a beloved dog and is looking to buy her first apartment.
It may sound premature for Megan to start her estate planning, but that's certainly not the case.
"If you do nothing and something happens, the state is going to decide how all of your money gets divvied up and you don't want that, even at this age," Dan said. "Maybe you have a friend, parents who helped you, or even a pet that you want to provide for in case of tragedy."
Dan adds that not taking the time to plan can only lead to outcomes that you don't want, even in your 20s.
"And secondly, as we keep saying, you have the ability to come back and change things every few years," he added. "Maybe you're not considering a trust right away. Maybe you're just trying to get a simple will. Something that dictates your plan."
Dan said Gen Z will grow into their estate plan as they get older, as their assets grow and as their families grow.
"This demographic also has newer investments like crypto and stocks through trading apps like Robinhood, so with this category, people also need to know passwords and how to access those newer investments in case something happens, so the money does not get lost," Dan added. It's smart for young adults to create a list of the assets that they own and their login information in a secure place.
"No matter the age group or your financial situation, it's always recommended to get a start now and then adjust your plan as needed," Dan said.
FAQs
Estate planning helps document your wishes for your assets, healthcare decisions and loved ones. Without a plan, state law may determine what happens to your property or who makes certain decisions if you become incapacitated.
Common documents may include a will, durable power of attorney and healthcare proxy. Depending on personal circumstances and state law, some people may also consider a trust or other planning tools.
An estate plan should be reviewed periodically and after major life changes such as marriage, divorce, the birth of a child, a move, new assets, retirement or the death of someone named in the plan.
Related articles

Practicing financial self-care means regularly checking in on your money habits, setting clear goals, and building simple routines that may help support your financial well-being over time.

Improving your financial fitness involves reviewing your spending, building a budget, paying down debt, and creating simple habits that may help you save and stay on track over time.

Saving for yourself and others involves getting organized, preparing key financial and legal documents, and planning ahead so you can manage responsibilities while protecting your own financial well-being.
Open an Account Today