


You are now leaving our website and entering a third-party website over which we have no control.
Today's Mortgage Rates1
Explore our mortgage solutions from closed or open mortgages with fixed or variable rate options to find the right mortgage rate for you. Understanding mortgage interest rates and Annual Percentage Rate (APR) can be helpful for saving in the long term.
Our Special Mortgage Rates
TD Mortgage Prime Rate is %
Compare Mortgage and TD Home Equity FlexLine rates
-
Fixed Rate Mortgages
-
Variable Rate Mortgages
-
TD Home Equity FlexLine (HELOC)
Get comfort knowing your interest rate won't increase over the term you select.
A fixed rate mortgage offers stability, and with it, peace of mind. Once you’ve selected your term, you can be assured your interest rate won't change for that period of time.
You can choose the term length: 6 month, 1, 2, 3, 4, 5, 6, 7 or 10 years.
|
Term |
Rate6 |
|---|---|
|
1 Year Open Mortgage |
|
|
1 Year Fixed Closed |
|
|
2 Year Fixed Closed |
|
|
3 Year Fixed Closed |
Posted rate: % |
|
4 Year Fixed Closed |
|
|
5 Year Fixed Closed |
Posted rate: % |
|
6 Year Fixed Closed |
|
|
7 Year Fixed Closed |
|
|
10 Year Fixed Closed |
A TD variable interest rate mortgage means the rate of interest is based on the TD Mortgage Prime Rate, which can go up and down over the term of a mortgage loan.
|
Term |
Rate |
|---|---|
|
5 Year Variable Closed Mortgage |
Posted Rate: Special Rate 2: % (TD Mortgage Prime Rate % %) |
|
5 Year Variable Open Mortgage |
A HELOC is an alternative to a mortgage. You get the option to borrow only what you need, as you need it. Plus, as it is secured by your real estate, you may get the benefit of an interest rate that is lower when compared to unsecured credit interest rates.
TD Home Equity FlexLine is a way to use your most powerful borrowing tool – your home. As you pay back the amount you owe, the amount of credit available to you increases until it reaches your credit limit. It’s available when you need it, through a variety of convenient options, 24/79.
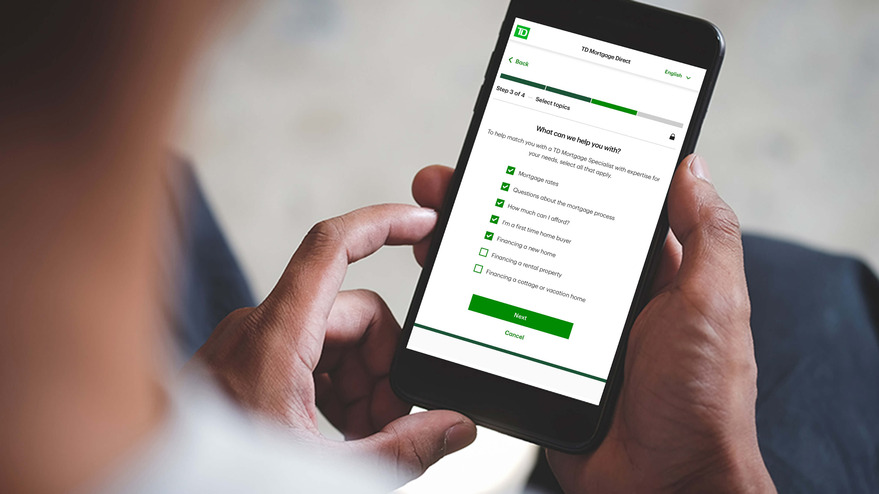
TD Mortgage Direct
Looking for tailored advice ASAP? Simply answer a few questions and TD Mortgage Direct will quickly match you with a Mortgage Specialist.
A TD Mortgage Specialist can help you:
- Understand fixed vs variable rate options and choose what works for you.
- Find a rate that works for you and switch to TD from another financial institution.
See how your mortgage rate impacts home affordability
Why get a TD Mortgage?
Mortgage interest rates FAQs
A fixed interest rate means your interest rate, along with your principal and interest payments, will stay exactly the same during your mortgage term.
With a variable interest rate, your interest rate can fluctuate based on changes in our TD Mortgage Prime Rate. While your payments will remain the same, the amounts from each payment that go toward the principal and interest can vary10.
It's important to take a closer look at the differences between fixed and variable interest rates before you make a decision.
A posted mortgage rate is the TD standard published rate for a mortgage term. A special mortgage rate is a discounted rate offered for certain TD mortgages and is lower than the applicable posted rate. Posted and special rates may change without notice.
Contact a TD Mortgage Specialist to discuss your situation and the mortgage rates that may be available to you.
The Bank of Canada overnight rate affects prime lending rates. TD Mortgage Prime generally moves with the Bank of Canada overnight rate, which can affect TD variable mortgage rates.
If TD Mortgage Prime increases, the interest rate on a TD variable rate mortgage increases. Your regular payment generally stays the same, but more of it goes toward interest and less goes toward the outstanding balance. If TD Mortgage Prime decreases, more of your payment goes toward the outstanding balance.
With a TD Mortgage Pre-Approval, the interest rate for the term chosen in your pre-approval can be held for 120 days, subject to all conditions. If the interest rate increases during that time, TD will hold your pre-approved rate if you meet all other conditions. Learn more about getting a TD Mortgage Pre-Approval.
If the interest rate for the term chosen in your TD Mortgage Pre-Approval decreases during the 120-day rate-hold period, you can ask TD to adjust your pre-approved interest rate to reflect the lower current rate. The adjustment is subject to the conditions of your pre-approval.
Discover more mortgage articles
Explore the Mortgage Learning Centre for articles that help you understand mortgage rates and compare your options. Learn how fixed and variable rates work, what can affect your payments and affordability, and how to make more informed mortgage decisions.
Other ways to connect
Find a rate that works for you
Find a rate that works for you